How to File Form 146 (Earlier Form 15CB) on the Income Tax Portal – Complete Step-by-Step Guide (FY 2026–27)
Learn how to file Form 146 (earlier Form 15CB) online for FY 2026–27 with this complete step-by-step guide. Understand CA assignment, taxpayer authorisation, remittance details, taxability, DTAA claims, TDS, UDIN, DSC-based e-verification, acknowledgement generation, and post-submission steps on the Income Tax e-Filing Portal.
Foreign remittances from India often require certification from a Chartered Accountant before the payment can be processed by the authorised dealer (AD) bank. Under the Income-tax Act, 2025, this certification is furnished through Form 146 (earlier known as Form 15CB).
This guide explains the entire filing process from assigning the form to your Chartered Accountant (CA) to successful submission and e-verification.
Note: Form 146 is generally applicable where a Chartered Accountant’s certificate is required before filing Form 145 (earlier Form 15CA). Whether Form 146 is mandatory depends on the nature of the remittance, its taxability and the applicable provisions of the Income-tax Act.
Part A – Assigning Form 146 to Your Chartered Accountant
Before a Chartered Accountant can prepare and file Form 146, the taxpayer must authorise the CA on the Income Tax e-Filing Portal.
Step 1 – Log in to the Income Tax e-Filing Portal
Visit the Income Tax e-Filing Portal and log in using your PAN, password and captcha.
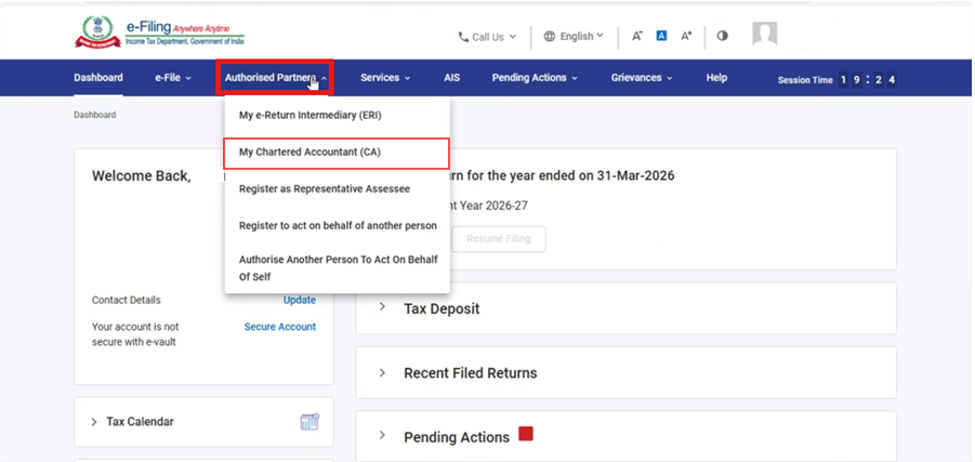
Step 2 – Open the Chartered Accountant Management Page
After logging in:
- Click Authorised Partners
- Select My Chartered Accountants (CA)
This section displays all Chartered Accountants linked to your account.
Why is this step necessary?
The Income Tax Department does not allow a CA to file Form 146 unless the taxpayer has first authorised the CA through the portal.
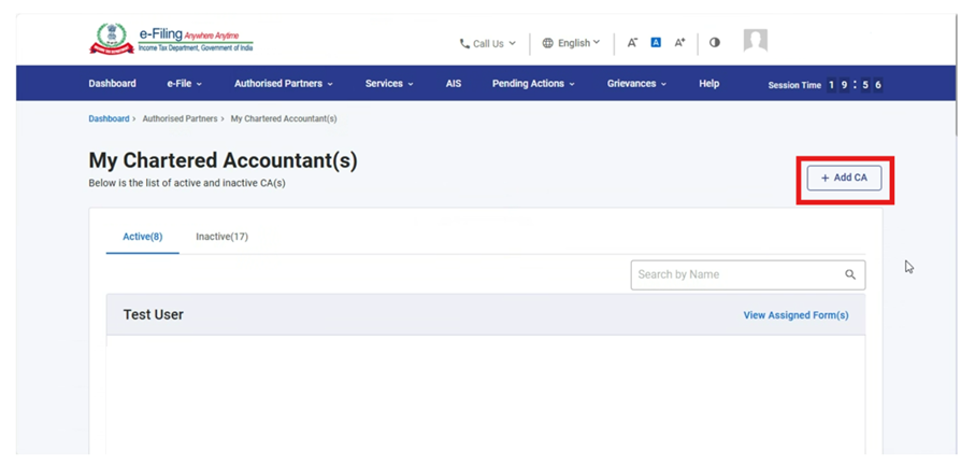
Step 3 – Add Your Chartered Accountant
Click Add CA.
You will be asked to enter:
- Membership Number of the Chartered Accountant
After entering the membership number, click Add.
The portal will automatically verify whether the membership number belongs to an active Chartered Accountant.
Step 4 – Assign Form 146
Once the CA has been added successfully, the portal will ask you to assign forms.
Select:
- Forms as per the Income-tax Act, 2025
- Form 146
Click Add.
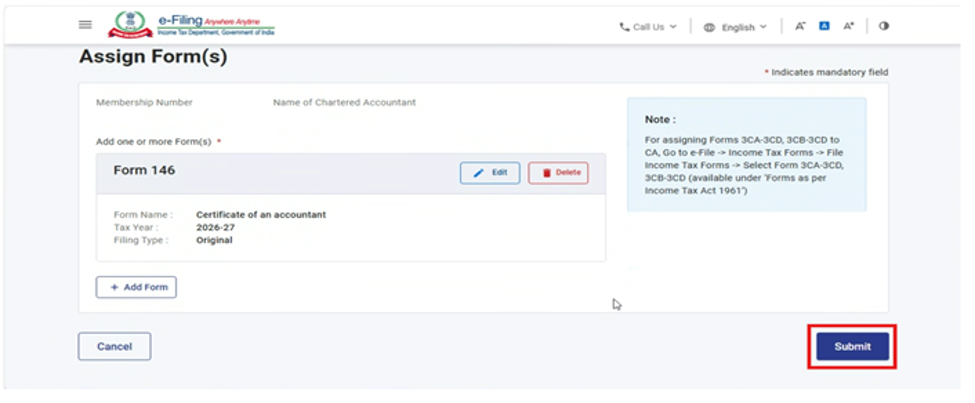
Step 5 – Submit the Assignment
Review the details.
Click Submit.
Once submitted, the Chartered Accountant will receive authorisation to prepare and file Form 146 on your behalf.
The taxpayer does not need to approve every entry in the form afterwards the CA will complete the form independently using the information and documents provided.
Part B – Filing Form 146 by the Chartered Accountant
After receiving authorisation, the Chartered Accountant can begin preparing the certificate.
Step 6 – Log in as a Chartered Accountant
The CA should log in using:
- User ID
- Password
- Captcha
The login should be through the Chartered Accountant account (ARCA login).
Step 7 – Open Form 146
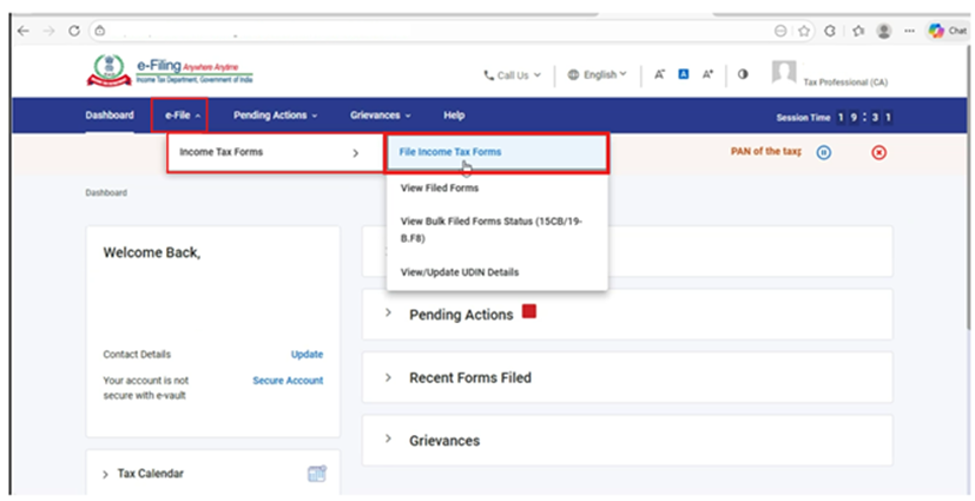
Navigate to:
e-File → Income Tax Forms → File Income Tax Forms
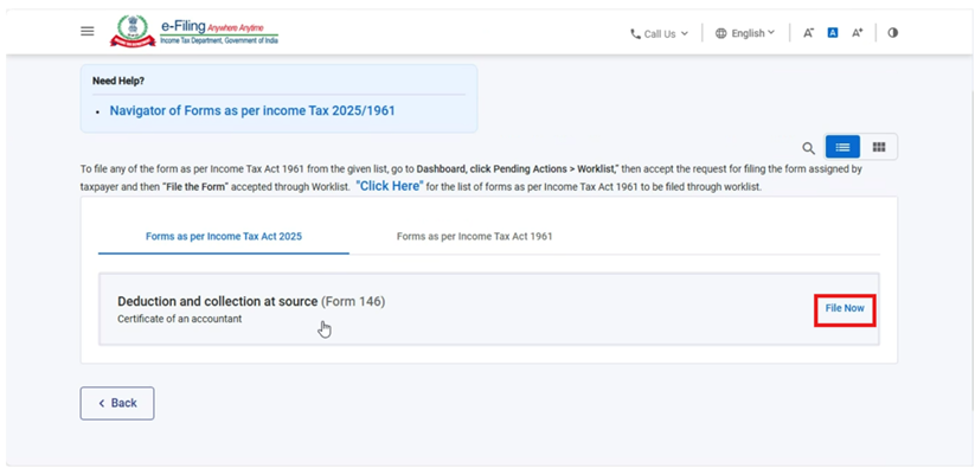
Search for:
Form 146
Click File Now.
Step 8 – Choose Tax Year and Submission Mode
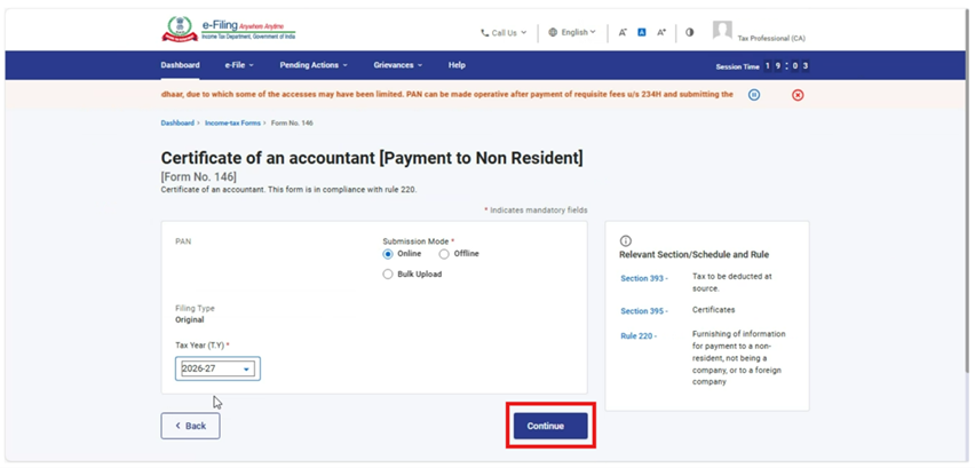
Select:
- Tax Year
- Submission Mode
Click Continue.
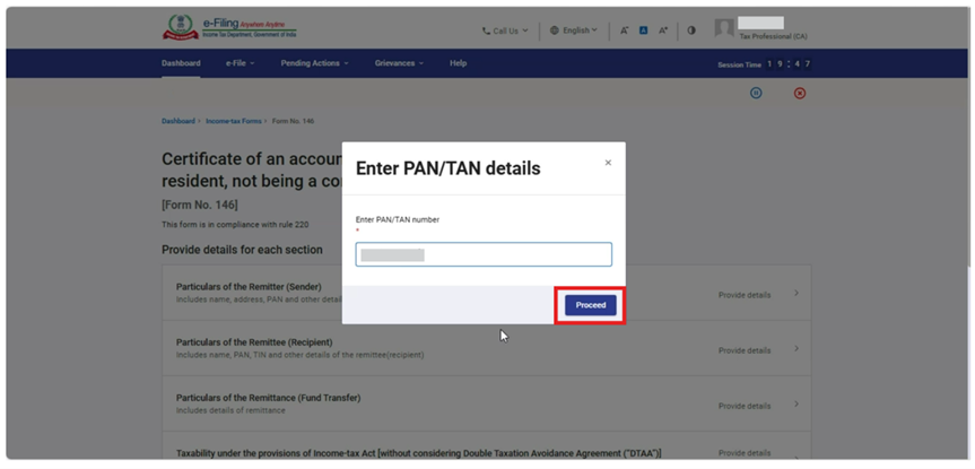
The portal will now ask for the PAN of the taxpayer who assigned the form.
Step 9 – Enter Taxpayer’s PAN
Enter the PAN of the remitter (taxpayer).
Click Proceed.
The portal will retrieve the taxpayer’s profile and open Form 146.
Completing Form 146
The form is divided into several sections. Each section must be completed before moving to the next.
Step 10 – Particulars of the Remitter (Sender)
Most details such as:
- Name
- PAN
- Address
will be automatically populated from the taxpayer’s PAN.
Verify that the information is correct.
Click Save.
Once saved, the panel status changes to Completed.
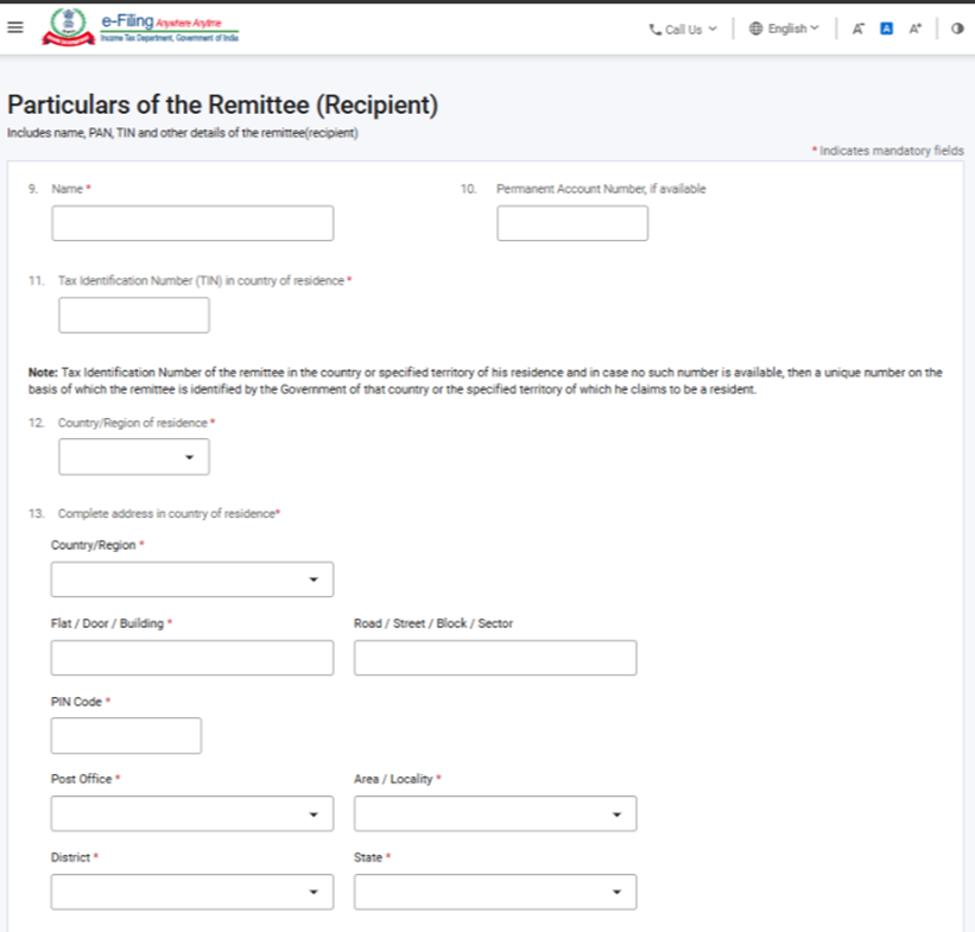
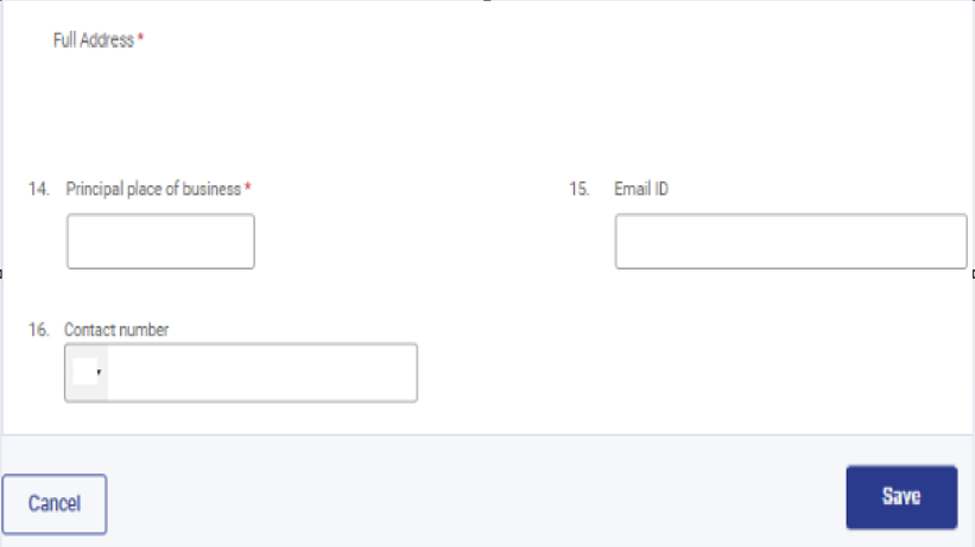
Step 11 – Particulars of the Remittee (Recipient)
This section captures details of the overseas recipient.
Provide:
- Name
- Country of residence
- Address
- Tax Identification Number (TIN), wherever applicable
- Residential status
- These details should match the invoice, agreement and Tax Residency Certificate (TRC), wherever available.
- Click Save.
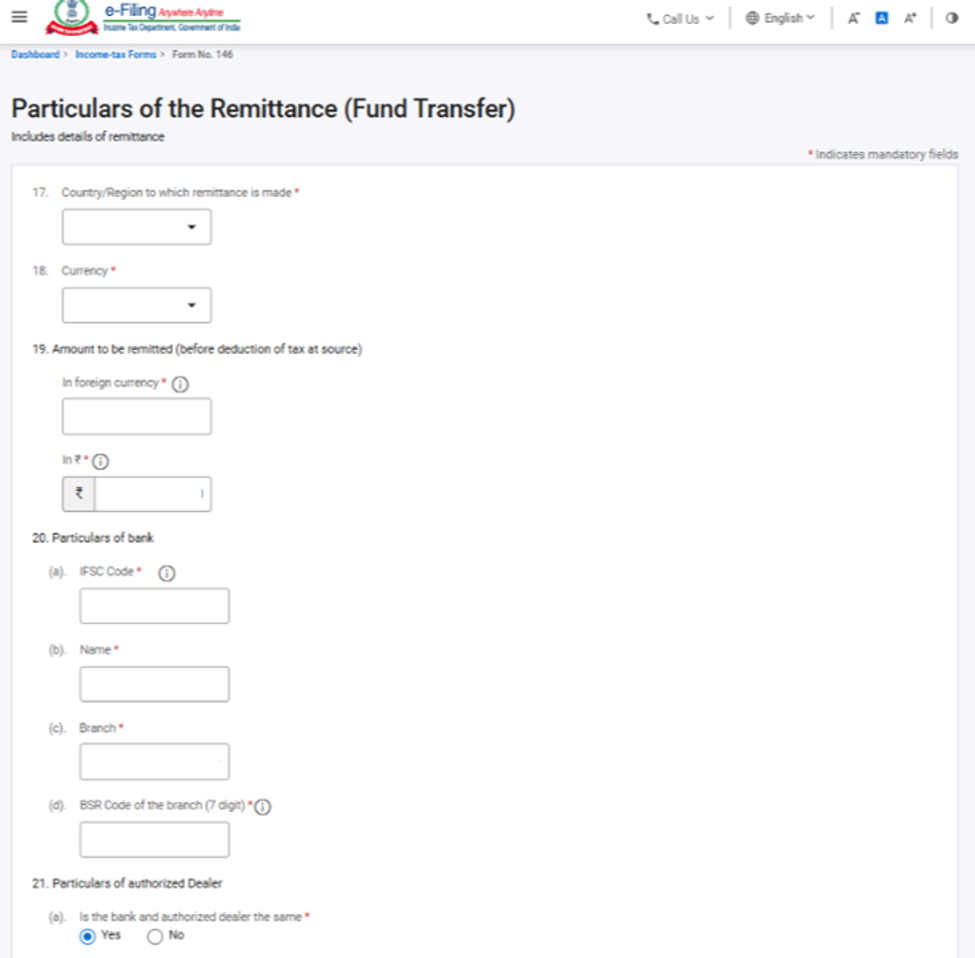
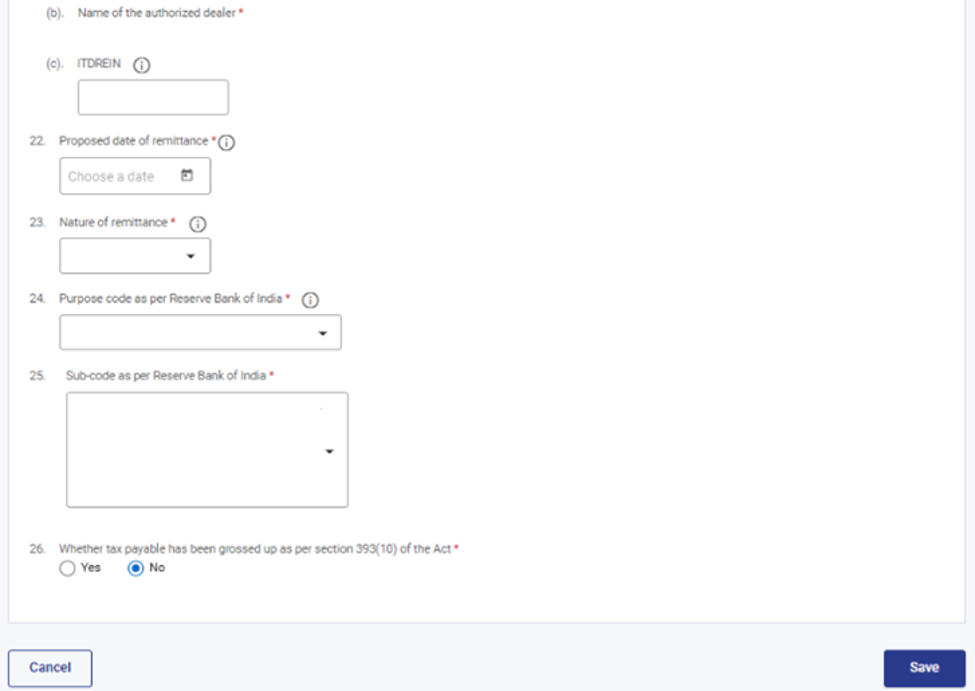
Step 12 – Particulars of the Remittance
This section records the actual payment being made.
Enter:
- Amount of remittance
- Currency
- Date
- Name of the bank
- IFSC
- Authorised Dealer details
- RBI Purpose Code
- RBI Purpose Sub-code
Important points
Amount of remittance
Always report the gross amount before deduction of TDS.
For example:
If the vendor is receiving USD 9,700 after deducting USD 300 as TDS, the amount to be reported is USD 10,000, not USD 9,700.
IFSC
Once a valid IFSC is entered, the portal automatically fills the bank name and branch details.
Always verify that the auto-populated information is correct.
Authorised Dealer
If the remitting bank itself is the Authorised Dealer, select Yes.
If another Authorised Dealer is involved, select No and choose the correct AD bank from the RBI list.
Purpose Code
The RBI Purpose Code determines the nature of the foreign remittance.
Examples include:
- Import of goods
- Royalty
- Software services
- Consultancy fees
- Technical services
- Selecting an incorrect Purpose Code may delay bank processing.
- Click Save.
Step 13 – Taxability under the Income-tax Act
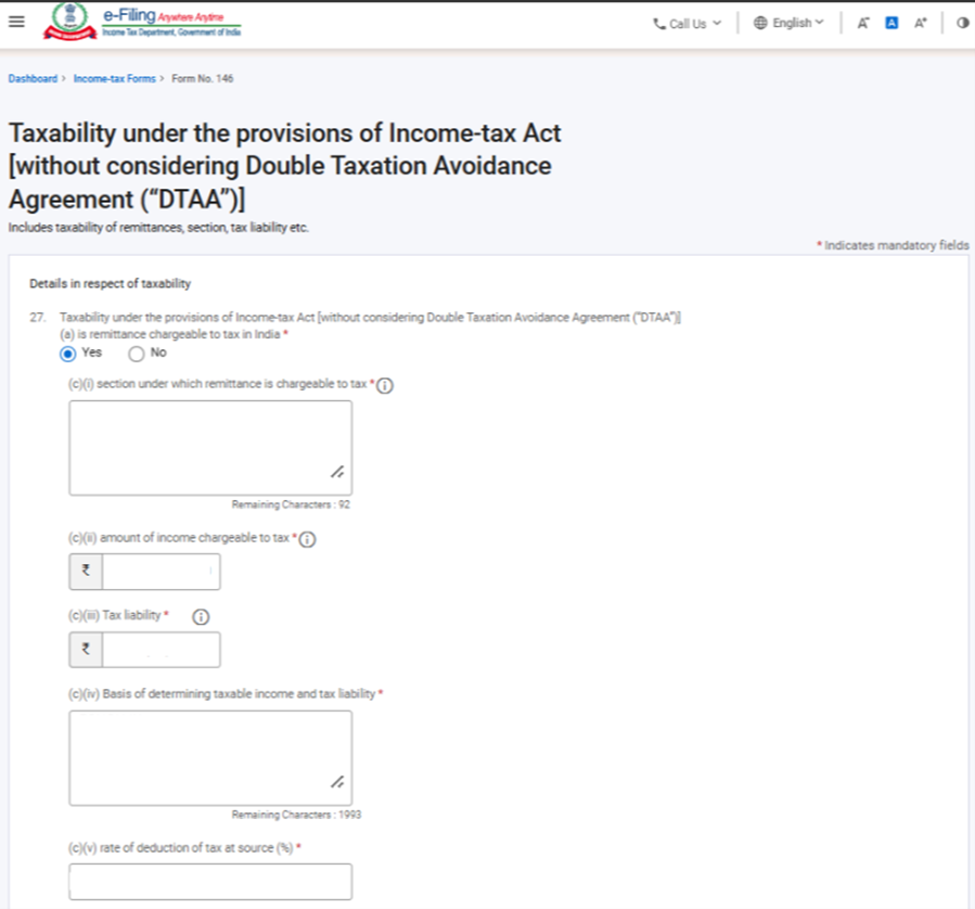
This is one of the most important sections of Form 146.
The CA must determine whether the payment is taxable in India under domestic tax law before considering any treaty benefits.
When should “Taxable in India” be selected as Yes?
Choose Yes if the payment is taxable under the Income-tax Act.
Examples include:
- Royalty
- Fees for Technical Services (FTS)
- Interest
- Dividend
- Certain professional services
- Capital gains taxable in India
The CA must then report:
Relevant section of the Income-tax Act
Amount chargeable to tax
Applicable tax rate
When should “Taxable in India” be selected as No?
Choose No if the payment is not taxable in India.
Examples include:
Import of goods
Reimbursement without any income element
Payments specifically exempt under the Act
Other transactions that are not chargeable to tax
The reason for non-taxability must be clearly stated.
Click Save.
Step 14 – Relief under DTAA
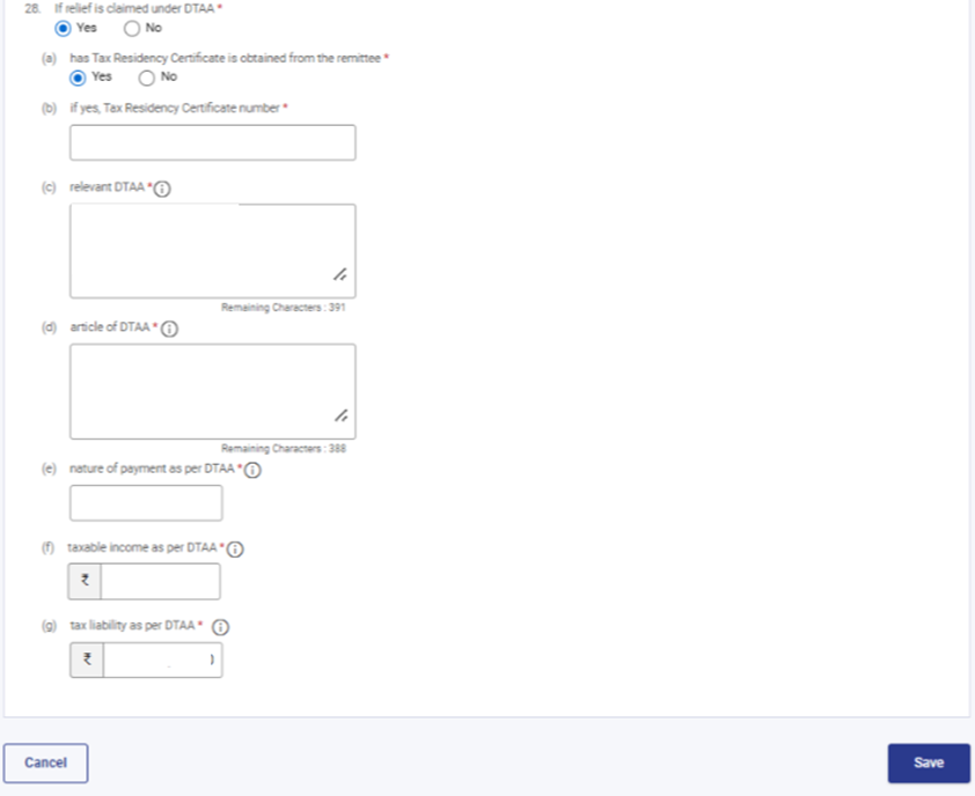
The portal asks whether relief under a Double Taxation Avoidance Agreement (DTAA) is being claimed.
Select “Yes” when:
- India has a tax treaty with the recipient’s country.
- The taxpayer intends to apply the treaty rate instead of the domestic tax rate.
- A valid Tax Residency Certificate (TRC) and other prescribed documents are available.
For example:
- Domestic tax rate: 20%
- DTAA rate: 10%
If all treaty conditions are satisfied, the lower DTAA rate can generally be applied.
Select “No” when:
- No DTAA benefit is available.
- The recipient has not provided a valid TRC.
- Domestic tax provisions are being followed without claiming treaty relief.
Where DTAA relief is claimed, provide:
- Country
- Relevant Article of DTAA
- TRC details
- Nature of payment
- Taxable income
- Tax amount
Click Save.
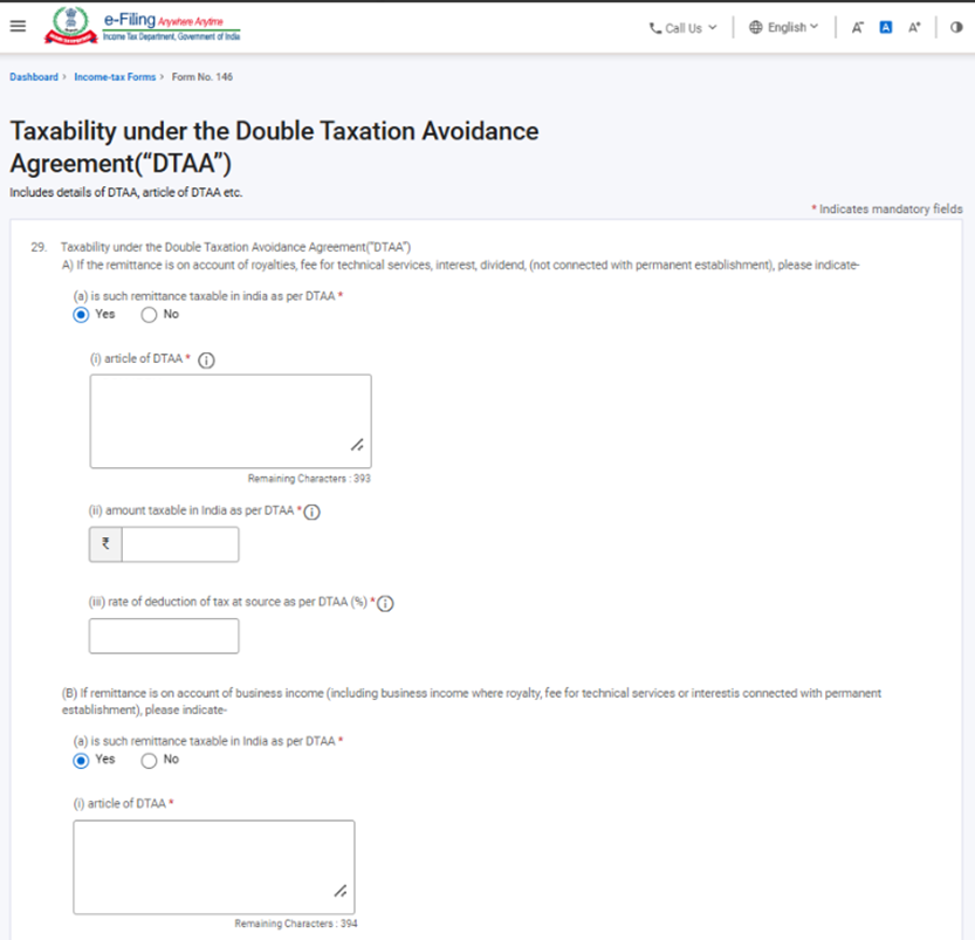
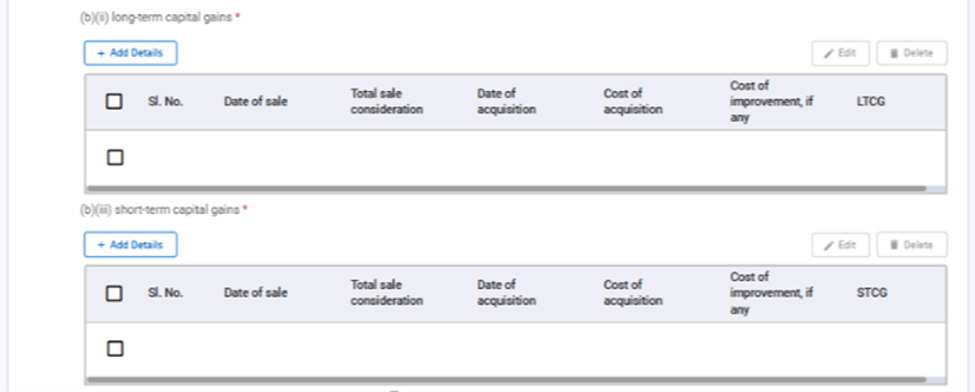
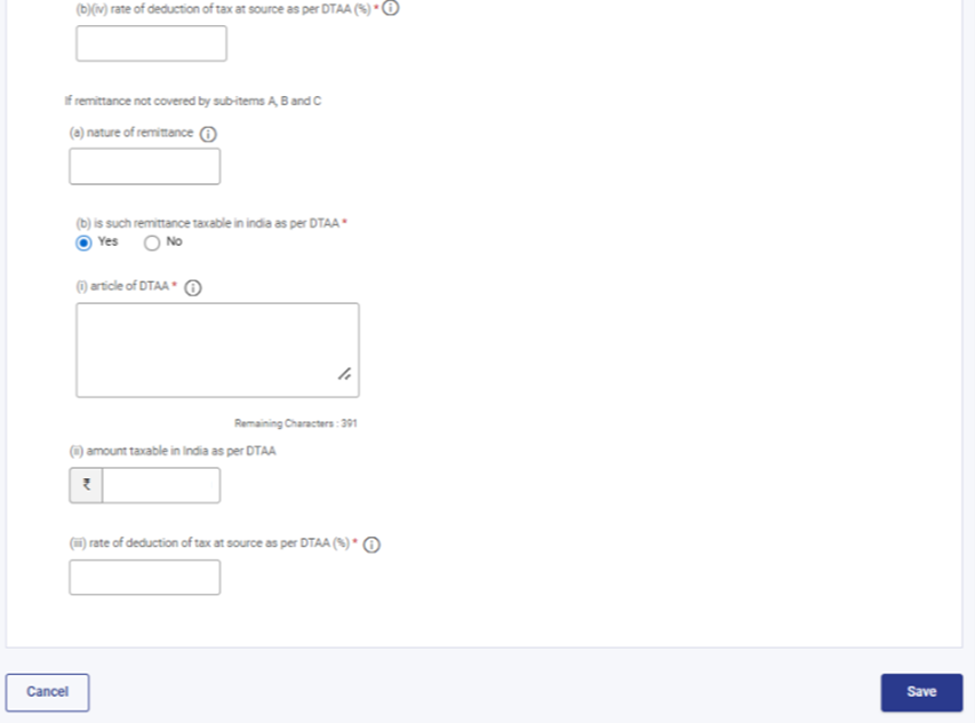
Step 15 – Taxability under DTAA
This section records the tax treatment after applying the treaty.
Where the payment relates to capital gains, additional details such as:
- Nature of capital asset
- Date of purchase
- Sale consideration
- Cost of acquisition
- Capital gain amount
must also be reported.
Click Save.
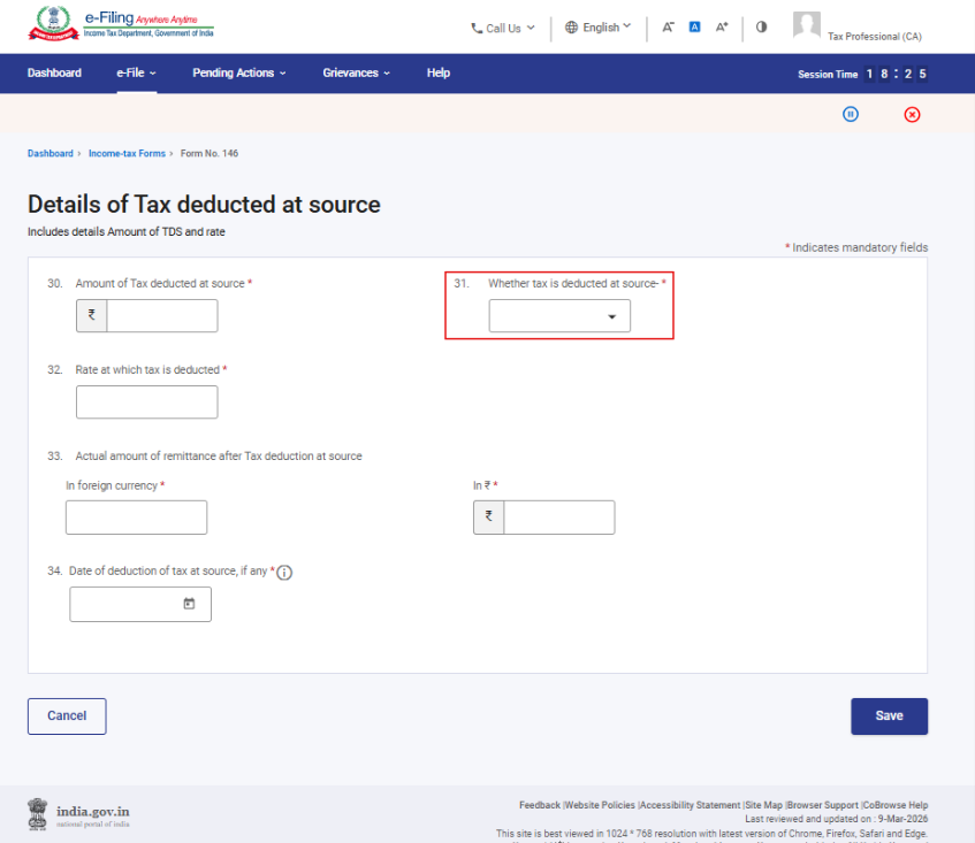
Step 16 – Details of Tax Deducted at Source (TDS)
Enter:
- Whether TDS has been deducted under the Income-tax Act or under DTAA.
- TDS amount.
- Date of deduction.
- Challan details, wherever applicable.
- Ensure that the TDS details match the actual deduction records.
Click Save.
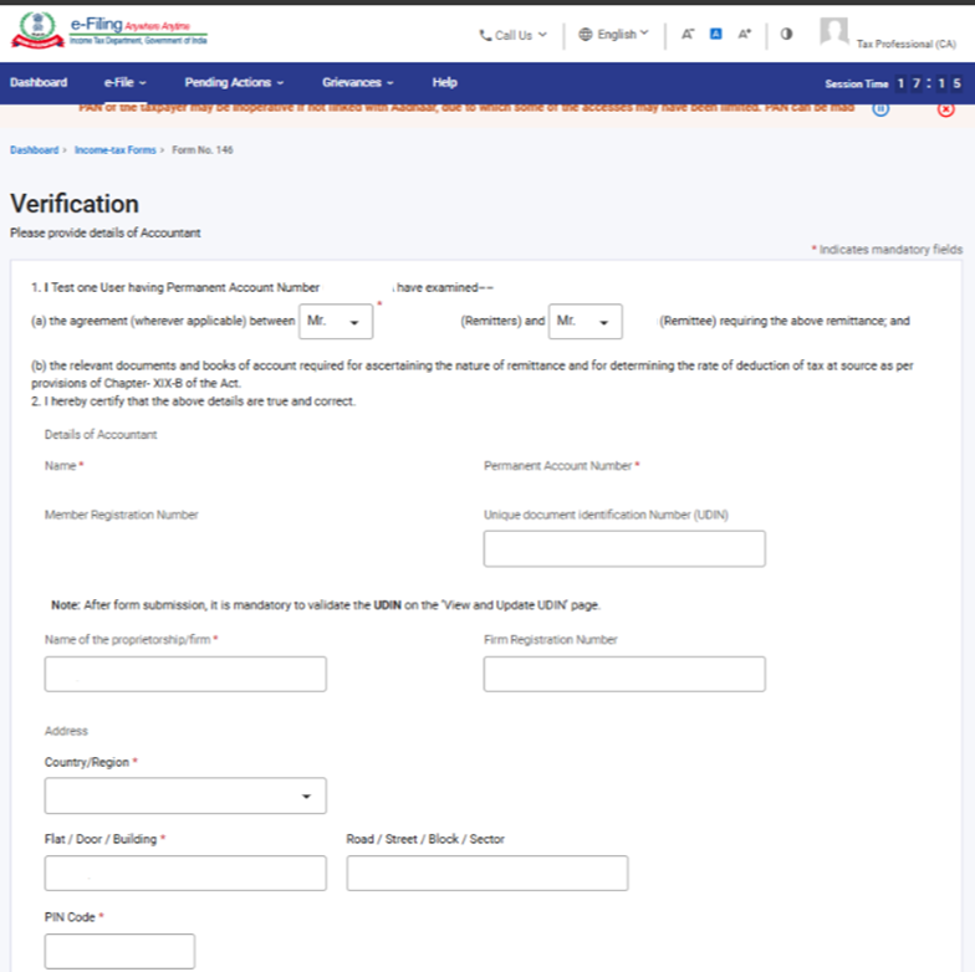
Step 17 – Verification
Complete the verification section.
The UDIN field is currently optional.
However, if a UDIN is entered, it must also be validated separately through the View and Update UDIN facility.
Click Save.
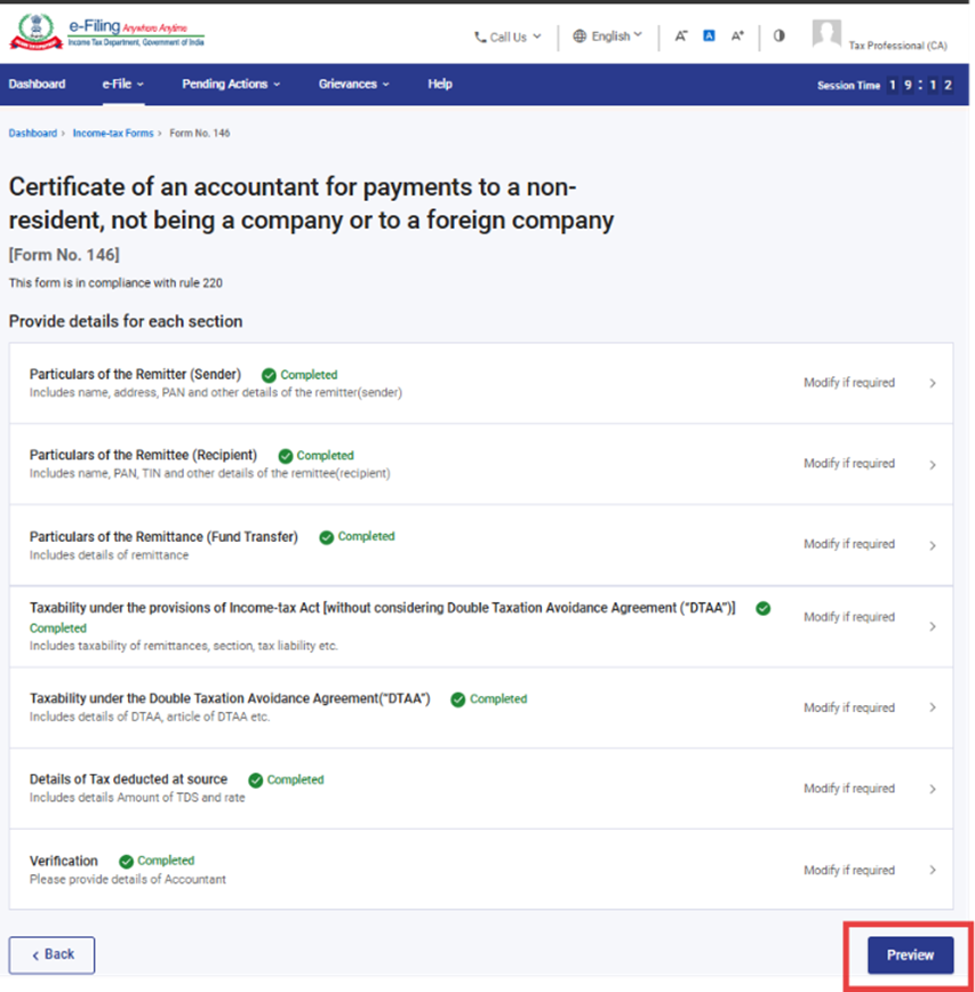
Step 18 – Preview the Form
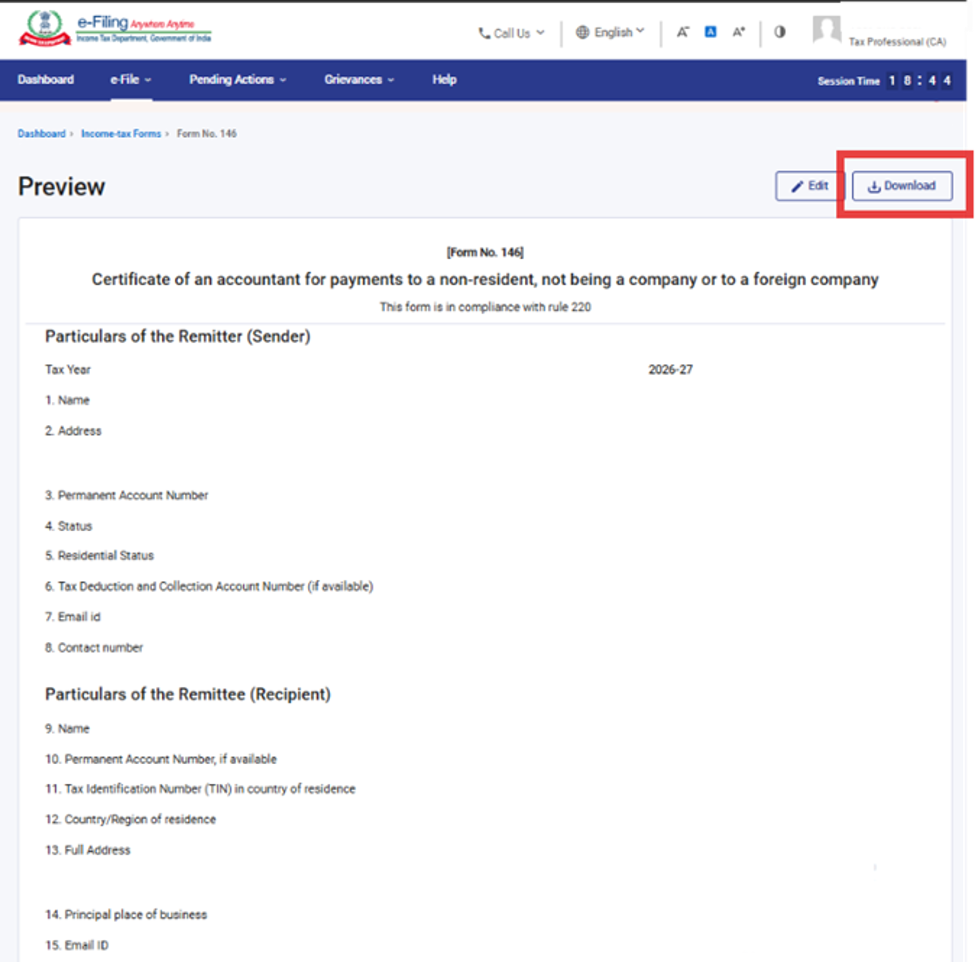
Click Preview.
Review every section carefully before submission.
You can also download the preview PDF for internal review or client confirmation.
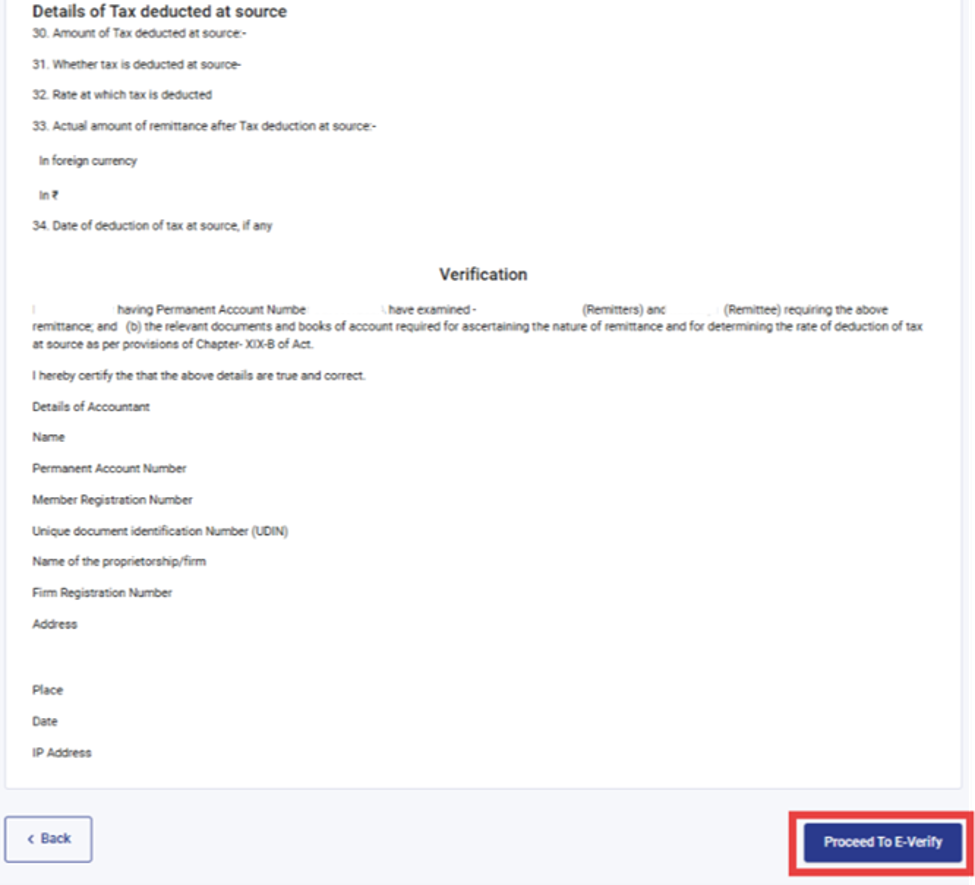
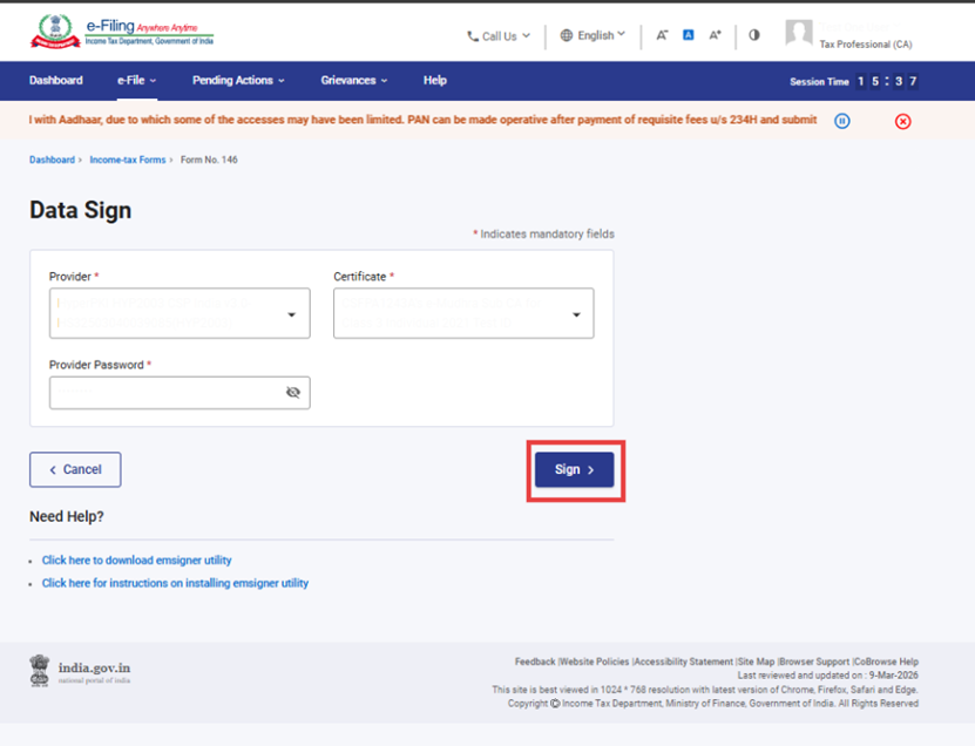
Step 19 – E-Verify the Form
Click Proceed to e-Verify.
Form 146 can presently be verified only through a Digital Signature Certificate (DSC).
Select the DSC.
Enter the DSC password.
Click Sign.
Step 20 – Successful Submission
Once the form is successfully submitted, the portal displays:
- Transaction ID
- Acknowledgement Receipt Number (ARN)
The taxpayer and the Chartered Accountant will also receive confirmation through their registered email ID and mobile number.
Save the acknowledgement for future reference.
After Submission
The filed Form 146 can be viewed by navigating to:
Dashboard → e-File → Income Tax Forms → View Filed Forms
If a UDIN has been entered, remember to validate it separately through the View and Update UDIN option.
Final Checklist Before Filing Form 146
- Taxpayer has authorised the Chartered Accountant.
- Remittance details are verified.
- RBI Purpose Code is correctly selected.
- Taxability has been analysed under the Income-tax Act.
- DTAA eligibility has been evaluated.
- TRC and supporting documents have been obtained, where applicable.
- TDS details are accurate.
- Form has been reviewed before e-verification.
- DSC is active and registered on the e-Filing Portal.
By following these steps carefully, taxpayers and Chartered Accountants can complete Form 146 accurately, minimise validation errors and ensure smooth processing of foreign remittances under the Income-tax Act, 2025.